Speculation is an inherent part of the government’s Autumn Budgets.
Every year, news outlets compete to correctly guess what will and won’t appear in a bid for your attention.
This noise can make you feel anxious about the security of your personal finances. Worse, it could result in a knee-jerk decision based on speculation rather than fact, which might put your wealth at risk.
This happened to retirees during the last government. As speculation grew about a possible reduction to pension lump sum tax benefits, many withdrew their pension wealth even though no such policy was announced.
In this article, we review how this played out ahead of the 2024 and 2025 Autumn Budgets, what it cost British savers, and how to avoid a repeat of history this year, in the lead-up to the event and in its aftermath.
Rumours about a loss of pension tax benefits caused retirees to withdraw £40 billion in savings
When the Labour government formed under Keir Starmer and Chancellor Rachel Reeves in 2024, many were braced for a substantial economic departure from the previous Conservative government.
This pressure compounded ahead of the 2024 Autumn Budget, resulting in widespread speculation about possible rules that could be introduced targeting personal wealth.
One main area of concern was the 25% tax-free lump sum.
Under current rules, you can usually withdraw up to 25% of your pension tax-free, up to the Lump Sum Allowance (LSA). The standard LSA is fixed at £268,275, although you might have a protected higher allowance.
However, rumours spread that the LSA would be reduced immediately following the Budget. In response, many retirees withdrew their lump sum pension entitlement ahead of time to protect their retirement wealth.
According to This is Money, this contributed to approximately £18 billion being withdrawn.
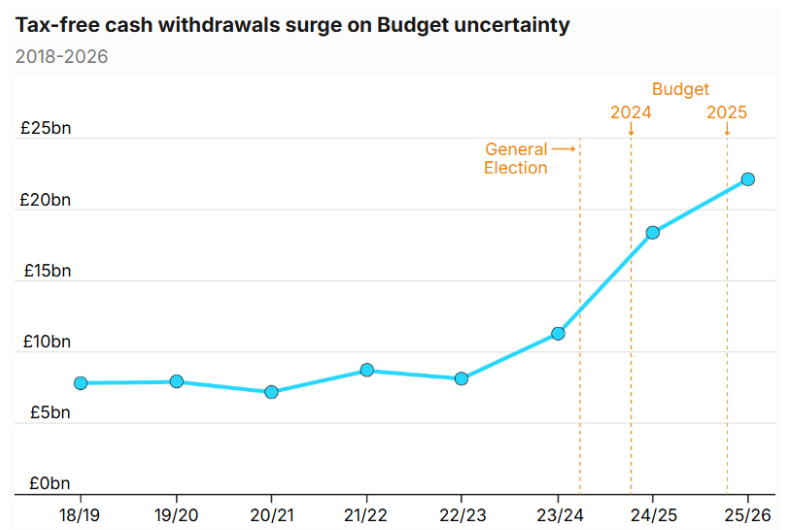
This phenomenon wasn’t unique to 2024. Similar speculation was revived in 2025, resulting in another £22 billion being prematurely withdrawn by retirees.
No tax-free cash rule changes were announced, leaving many retirees potentially worse off
The disproportionate level of coverage the LSA received made it seem as though a policy change was set in stone, rather than based on opinion.
Ultimately, no such policy materialised at either Budget. Those who had withdrawn their tax-free cash entitlement faced several consequences:
- For some, the decision was irreversible, and they could not deposit their tax-free lump sum back into their pension fund.
- Taking 25% of their pension as tax-free cash significantly reduced the amount of wealth left to benefit from investment growth.
- Once withdrawn, options for storing pension lump sums tax-efficiently were limited, and wealth became more vulnerable to inflation, which can erode your money’s spending power.
The decision to withdraw pension lump sums early was motivated by a desire to preserve tax benefits. But those who did so may have found themselves with limited options for preserving the tax efficiency of their retirement wealth moving forward.
Learn more: Why advice is key before you take pension tax-free cash
Similar fears are being stoked ahead of the 2026 Autumn Budget
The government has been overhauled since the last Autumn Budget, with Keir Starmer stepping down as prime minister and Andy Burnham taking his place.
Burnham has announced several new policies since taking office on 20 July, such as a future National Care Service, changes to the State Pension triple lock from April 2030, and an ambitious new council housing programme.
These policies have called into question how Burnham and Chancellor John Healey plan to allocate funding. According to the BBC (citing Institute for Fiscal Studies research), the government could be facing a gap of around £35 billion, based on Healey’s plan to increase defence spending combined with external factors like rising inflation.
Speculation about possible tax rises being used to fill this gap has taken centre stage, as have resurgent doubts about the ongoing integrity of the pension lump sum. We won’t know what policies have made it into the Budget until the day, but even then, it might be best to step back and let the dust settle.
Remember: avoid making pension decisions based on speculation alone
The past two Autumn Budgets prove that taking action based on speculation can leave you worse off in the long run.
While neither Burnham nor Chancellor John Healey has guaranteed that pension tax-free cash is safe from change, making a knee-jerk decision now might only limit your choices in the future.
Likewise, it’s important to remember that some Budget changes don’t take effect immediately. While they may be announced on 28 October, it could be years until rules come into force, giving you plenty of time to react and formulate a plan rather than rush into a decision.
The best course of action may be to wait until policies are announced during the Autumn Budget. If you were already planning to withdraw your tax-free pension lump sum, your situation may be different.
Speak to us if you’re concerned
If you’re nervous about the upcoming Budget and how it might impact your retirement wealth, speak to a member of our team today.
Email info@thepensionplanner.co.uk or call 0800 0787 182.
Please note
This article is for general information only and does not constitute advice. The information is aimed at individuals only.
All information is correct at the time of writing and is subject to change in the future.
A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance.
The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts.
 Production